Why Commercial Property Deserves a Place in Your WA Investment Strategy
If you have built your property portfolio around residential, stepping into commercial property can feel like a completely different world.
In many ways, it is.
The finance is different. The leases are different. The due diligence is more involved and there are different risks to understand.
But for the right buyer, commercial property can offer strong income, longer term tenants and opportunities that simply do not exist in residential property.
For business owners, there is also the potential to purchase premises through a Self Managed Super Fund and lease the property back to their own business, subject of course to the appropriate structure and professional advice.
At Beagl, we are seeing more investors and business owners wanting to understand whether commercial property should form part of their broader strategy.
So, what should you actually be thinking about?
Why Consider Commercial Property?
Stronger income potential
One of the first things that attracts investors to commercial property is yield.
Depending on the property, location, tenant and lease, commercial yields can sit well above what you would typically expect from residential property.
The lease structure can also make a significant difference to your actual return.
With many commercial leases, the tenant contributes towards or pays a range of property outgoings. This might include council rates, water charges, insurance and, in some cases, other property expenses.
Compare that with residential property, where most of those costs remain firmly with the owner.
That does not mean every commercial property produces great cash flow. Far from it.
The lease needs to be properly understood, because the headline yield only tells part of the story.
We want to know what the tenant actually pays, what the owner remains responsible for and, most importantly, what is left in your pocket once everything is accounted for.
Owning Your Business Premises Through Your SMSF
For business owners, this is often where the commercial property conversation becomes particularly interesting.
Subject to the relevant rules and professional advice, an SMSF may be able to purchase qualifying business real property and lease it to a related business on genuine commercial terms.
Put simply, instead of your business paying rent to somebody else's landlord, there may be an opportunity for that rent to contribute towards an asset held within your superannuation structure.
It can be a very appealing strategy, but it needs to be set up correctly.
The lease needs to reflect market terms, the structure needs to comply with SMSF requirements and the transaction needs to make sense independently of the tax or superannuation benefits.
This is where we strongly encourage clients to have their accountant, financial adviser, broker and lawyer involved early.
Our role is to work alongside those advisers and make sure the property itself stacks up.
Commercial Finance Is Different
This is an area where buyers can get caught out if they approach a commercial purchase in the same way they would a residential one.
Commercial lenders look closely at the property, the borrower, the lease, the tenant, the intended use and the strength of the overall transaction.
Loan to value ratios are generally lower than residential lending, which means buyers often need to contribute more equity.
Specialised properties can be treated differently again.
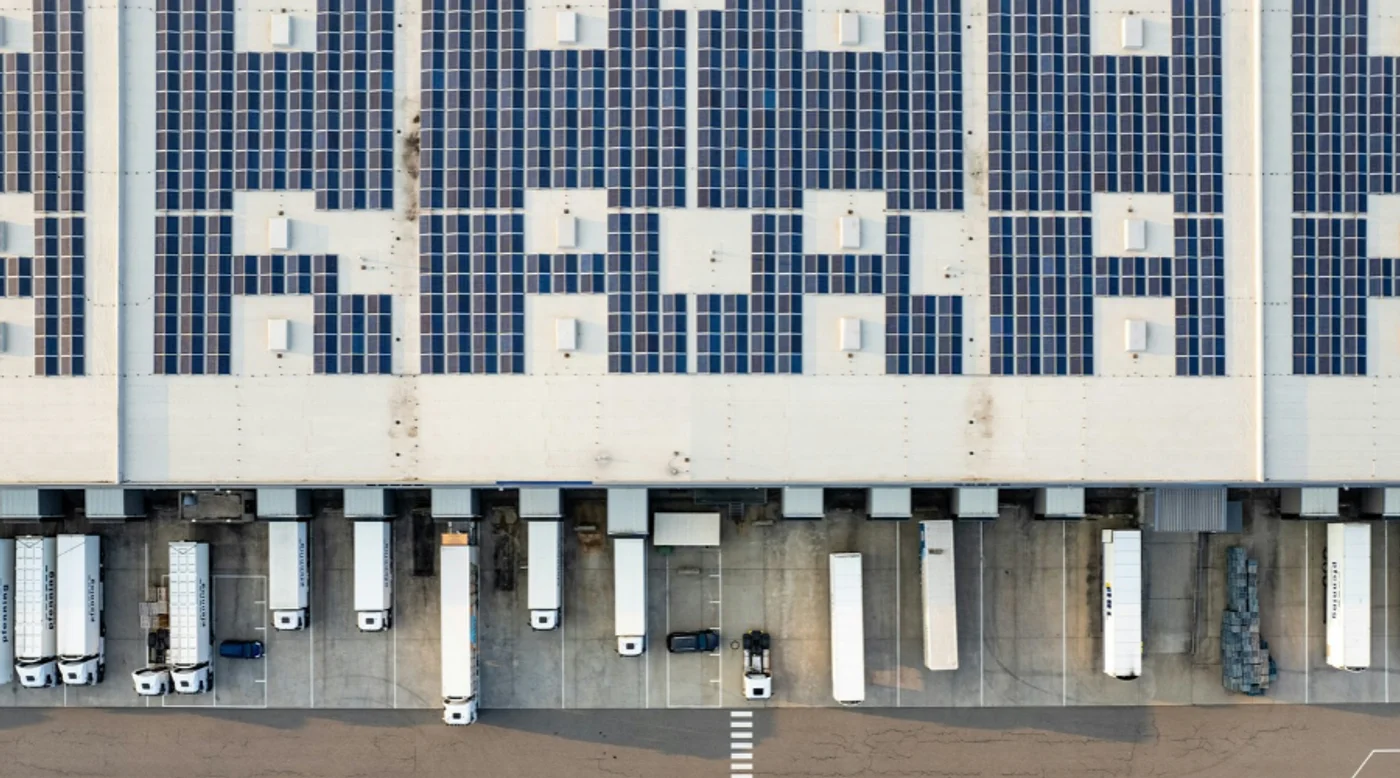
A lender may look very differently at a standard warehouse in an established industrial precinct compared with a highly specialised building that could be difficult to lease or sell to another operator.
SMSF lending adds another layer of complexity and may require specific ownership and trust structures.
For this reason, we like the finance conversation happening before we get serious about a property.
There is little value in finding a fantastic commercial opportunity only to discover that the finance structure does not work.
The Risks You Need to Understand
Commercial property can perform extremely well, but there are some fundamental differences that buyers need to understand before jumping in.
Vacancy can hurt
Vacancy is probably one of the biggest risks.
A residential property in a strong location may only be vacant for a relatively short period. Commercial property can be very different.
Depending on the asset, location and intended use, finding the next tenant could take months.
If the property is highly specialised, the pool of potential tenants may be smaller again.
This is why we look beyond the current rent.
A strong lease and a quality tenant can add significant value to a commercial asset.
A weak tenant or an approaching lease expiry can change the picture very quickly.
GST needs to be understood before you buy
GST is another area where commercial transactions differ considerably from most residential purchases.
Depending on the transaction, GST may apply, or the property may potentially be sold as a going concern if the relevant requirements are satisfied.
The structure can have a significant impact on the amount of money required to complete the purchase and should be understood before signing a contract.
We are not accountants and we do not pretend to be.
Our job is to identify these issues early and make sure the right advisers are involved before our client becomes committed.
Capital growth works differently
Commercial property is often valued heavily on the income it produces.
Rent, lease terms, tenant quality and the market yield investors are prepared to accept can all have a direct impact on value.
That means commercial property should not simply be viewed as residential property with a better rental return.
It is a different investment.
You need to understand the income, the lease, the tenant, the building itself and what the property could realistically be worth to another buyer in the future.
Due Diligence Matters
This is probably the part of commercial property we enjoy most at Beagl.
There is a lot to unpack.
We look at the property, the location, zoning, permitted use, leases, outgoings, access, parking, approvals, building condition and future capital expenditure.
We consider the strength of the tenant and the lease.
We look at comparable rents and sales.
We consider what happens if the current tenant leaves.
For owner occupiers, the questions are different
For an owner occupier, the questions are different again.
The purchase price is only one part of the decision.
Commercial Property Can Be an Excellent Strategy, When the Property Stacks Up
We are not here to tell every investor they should buy commercial property.
For some buyers, residential will remain the better fit.
For others, commercial can provide strong income, diversification and a completely different way of building long term wealth.
For business owners, owning the premises they operate from can also be worth exploring, particularly where an SMSF strategy may be appropriate.
The important thing is to buy the right property, for the right reason, with the right structure around it.
That is where Beagl comes in.
We source opportunities, assess the property and its commercial fundamentals, undertake due diligence, negotiate the purchase and work alongside your broker, accountant, lawyer and settlement agent to keep the process moving.
Whether you are looking for your first commercial investment, adding to an existing portfolio or considering purchasing premises for your own business, we can help you work through the opportunity and determine whether it genuinely stacks up.
Thinking About Buying Commercial Property in WA?
Get in touch with Beagl and let’s have a conversation about what you are trying to achieve.
This article provides general information only and does not constitute financial, taxation, legal or SMSF advice. Buyers should obtain independent professional advice relevant to their individual circumstances before making an investment decision.